Which AI Tool Can Separate IDX Opening Gaps from Intraday Moves?
An ICBP Chat walkthrough separates a 5.50% opening gap from the subsequent intraday fall—and shows why the underlying rows and absolute-gap ranking need checking.
By Trade Inc Research

Trade Inc Chat can help separate an IDX stock’s overnight opening gap from what happened after the market opened. In this ICBP walkthrough, a 5.50% gap up was followed by a 5.54% fall from open to close. Those are different measurements—not a profitable trade.
The useful output is a dated table you can check, not an unchecked “biggest movers” answer. This demonstration required two correction prompts before the ranking matched an independent calculation. We show that limitation because it affects whether this workflow fits your needs.
This guide is published by Trade Inc about its own product. It uses an authenticated Pro workspace, not a free calculator. Product access was checked on 9 October 2026; the historical example ends on 6 October.
Key takeaways
- Ask for the previous stored session’s close, the open and the same-day close.
- Rank by absolute gap size if both upward and downward gaps matter.
- Check the underlying rows: the first answer and its first revision contained errors.
- A gap table describes prices. It does not establish a cause, an executable entry or a backtested strategy.
Start with a bounded question in Chat
Open Trade Inc, sign in, choose Percakapan / Chat, and enter the ticker, dates and formula in the message box. Press Kirim / Send. Our demonstration used the Cepat response mode.
The public product page describes custom analysis and AI research within the Pro workspace. That supports the product category; the screenshots below document this particular test, not a promise that every request will return the same output.
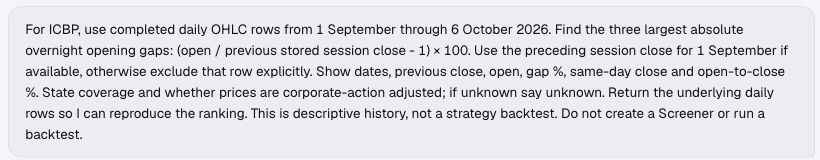
The submitted question defines the window and asks for source rows, rather than merely asking which day “jumped most.”
A reusable version of the request is:
For ICBP, use completed daily price rows from 1 September through 6 October 2026. Calculate each opening gap as (open / previous stored session close − 1) × 100. Rank the three largest absolute gaps, including negative gaps. Show the previous close, open, same-day close and open-to-close change. Return the underlying rows, count the eligible sessions and state whether prices are adjusted for corporate actions. Do not run a backtest or create a Screener.
Include one preceding session before the requested start. Here, 31 August supplies the Rp7,600 close needed for 1 September. “Previous session” is not necessarily yesterday’s calendar date.
Check the calculation before interpreting the result
Our initial answer used incorrect previous closes for two dates and overstated the eligible row count. A follow-up corrected those issues but still omitted a negative gap from the top three. A second correction explicitly compared its absolute size with the positive gap it should replace.
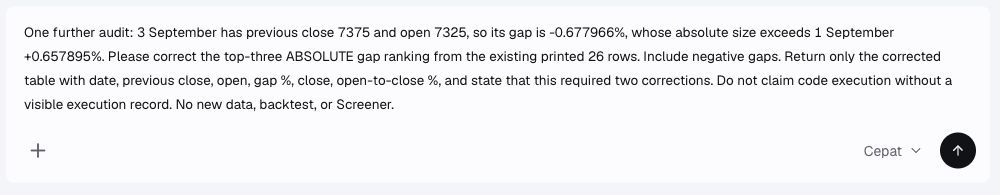
The correction points to exact input values. It does not simply ask the model to be more confident.
An independent calculation over the 26 eligible stored sessions reproduced the final table. The relevant daily open and close values also matched a fresh read-only retrieval on 9 October.
| Session | Previous close (Rp) | Open (Rp) | Opening gap | Close (Rp) | Open to close |
|---|---|---|---|---|---|
| 7 Sep 2026 | 7,275 | 7,675 | +5.4983% | 7,250 | −5.5375% |
| 6 Oct 2026 | 6,825 | 6,875 | +0.7326% | 6,800 | −1.0909% |
| 3 Sep 2026 | 7,375 | 7,325 | −0.6780% | 7,375 | +0.6826% |
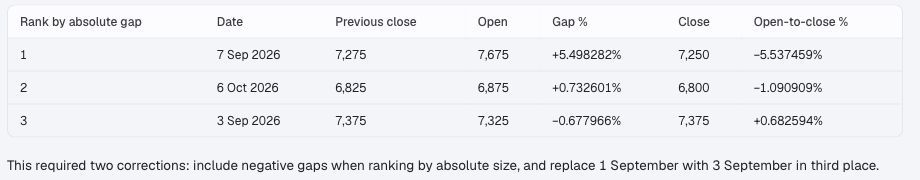
Corrected output. The third row is negative: −0.6780% has a greater absolute size than 1 September’s +0.6579%.
To reproduce it, sort daily rows by date, shift the close by exactly one row, calculate the gap, then filter the requested window and sort by absolute gap. Calculate the second return separately: (same-day close / open − 1) × 100. Round only after sorting.
The earlier response said it executed code, but we did not verify a visible execution record. Our validation is the independently reproduced arithmetic, not that statement.
What the ICBP example actually tells you
On 7 September, the opening price was Rp400 above the previous close. By the close, it was Rp425 below the open and Rp25 below the preceding close.
That separates three different stories: a positive opening gap, a negative intraday move, and a small negative close-to-close move. Adding the two percentages is not exact because they use different denominators.
It does not tell us why the opening differed, whether an investor could transact at those prices, or whether buying or fading gaps would work. Those questions require event evidence or an explicitly defined strategy evaluation.
Who should use this workflow?
It suits a researcher who wants to investigate a particular stock and can inspect the returned inputs. It is less suitable if you need an unattended, error-free ranking: this example required human-directed corrections.
For a single pair of prices, a spreadsheet or calculator may be enough. Chat is more useful when you want to request the rows, compare definitions and continue the investigation in the same conversation.
Corporate-action adjustment status remains unknown. The observations describe stored prices, not dividend-adjusted total returns; no fees, fills or trading rule were modeled. A corrected or missing source row could change the ranking. Before treating a large gap as an event-driven move, verify the price basis and relevant disclosures.
For adjacent questions, see volume-breakout checks, daily versus weekly charts, and verifying AI research.
This article is for research and information only. It is not personalized financial advice or an instruction to trade.